What is the scope and industry significance of the Pre-Analytical Automation Market?
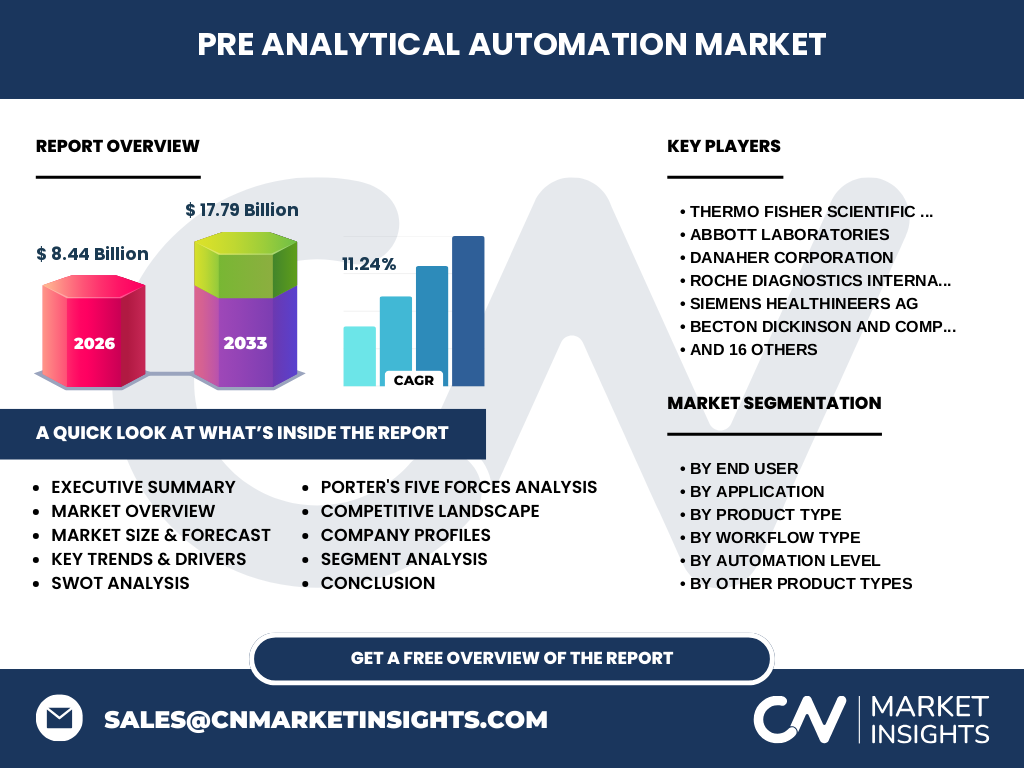
Our analysis indicates that the Pre-Analytical Automation Market valued at 8.44 Billion in 2026, encompasses robotic sample preparation, sorting, transport, and storage systems that eliminate manual laboratory bottlenecks. This ecosystem ensures specimen integrity under strict FDA and CE-IVD guidelines, significantly reducing pre-analytical error rates across high-throughput hospital networks.
Key market drivers, restraints, challenges, and opportunities shaping Pre-Analytical Automation Market
Severe clinical labor shortages and soaring specimen volumes act as primary structural growth drivers. Conversely, prohibitive capital expenditure requirements for modular tracks constrain adoption among regional facilities. Regulatory compliance hurdles regarding barcode traceability and data security present persistent operational challenges, yet expansion into emerging molecular diagnostics workflows unlocks lucrative opportunities for agile vendors.
Emerging trends and growth patterns in Pre-Analytical Automation Market
The shift toward total laboratory automation dominates current procurement cycles. Laboratories increasingly demand seamless middleware integration to connect automated sample sorting with downstream clinical chemistry and immunoassay analyzers, maximizing throughput while minimizing manual touchpoints for critical patient specimens.
How did COVID-19 impact the Pre-Analytical Automation Market and shape its recovery trajectory?
The pandemic exposed acute vulnerabilities in manual sample handling during unprecedented PCR testing surges. Post-pandemic recovery has accelerated capital influx into automated sample preparation and high-density storage systems, as diagnostic laboratories future-proof their operations against sudden epidemiological spikes and staffing constraints.
Competitive Benchmarking: Major players, market concentration, and strategic dynamics
The competitive landscape features high concentration among multinational diagnostics titans such as Roche Diagnostics, Siemens Healthineers, and Danaher. These incumbents leverage expansive installed bases of clinical chemistry analyzers to bundle proprietary track systems, while specialized players like Inpeco SA and Tecan Group carve out niches through OEM middleware partnerships.
Executive Summary: High-level synthesis of key findings about Pre-Analytical Automation Market
Driven by compounding clinical demands, the market is poised for robust expansion. Strategic investments in automated sample transport and nucleic acid extraction workflows are critical for laboratories aiming to mitigate human error and optimize turnaround times in high-volume environments.
Market Forecast: Projected growth trajectory from 2027 to 2033
Our proprietary modeling projects the market to expand from 2027 to 2033, reaching an impressive 17.79 Billion by the end of the forecast period at a robust CAGR of 11.24%. This acceleration reflects sustained enterprise spending on end-to-end laboratory optimization.
Segmentation Analysis: Breaking down product types, workflows, and end-users
The ecosystem is segmented by workflow type into standalone and integrated automation systems, and by product type encompassing automated sample preparation, transport, sorting, and storage. Diagnostic laboratories and hospitals represent the dominant end-user segments, prioritizing high-throughput clinical chemistry and molecular diagnostics modules.
Geographic Distribution: Regional market analysis and performance dynamics
Regional performance is heavily anchored by North America and Western Europe, driven by stringent reimbursement frameworks and early adoption of total laboratory automation. Meanwhile, Asia-Pacific exhibits the fastest regional growth, propelled by massive healthcare infrastructure upgrades in urban medical hubs.
In-Depth Regional Review: Key markets and localized constraints
North American growth is sustained by hospital network consolidation and stringent CLIA quality mandates. In contrast, APAC expansion navigates complex cross-border logistics for sensitive biological reagents, favoring localized distributor networks for automated guided vehicle systems and robotic transport tracks.
Strategic Positioning of Leading Companies in Pre-Analytical Automation Market
Industry leaders maintain distinct strategic moats. Becton Dickinson and Company focuses on superior specimen collection and pre-analytical integration, whereas Thermo Fisher Scientific Inc. leverages comprehensive liquid handling systems and nucleic acid extraction portfolios to dominate molecular workflows.
Porter's Five Forces Analysis: Assessing competitive intensity and market pressures
Industry rivalry is intense, dominated by established IVD giants possessing extensive patent portfolios. Supplier power remains moderate due to specialized requirements for robotic components, while high switching costs associated with proprietary track systems effectively mitigate the threat of new market entrants.
SWOT Analysis: Internal capabilities and external market dynamics
Core strengths include unmatched throughput and error reduction, balanced against high initial capital expenditures as a primary weakness. Key opportunities lie in expanding molecular and microbiology automation, while strict cybersecurity threats for laboratory information systems pose notable external risks.
Value Chain Analysis: Industry structure from raw materials to end-users
The value chain initiates with high-grade polymers, precision sensors, and optical components sourced by specialized component manufacturers. Value aggregation occurs during systems integration by automation vendors before delivery to hospitals, research institutes, and commercial reference laboratories.
Strategic Investment Insights and High-Potential Areas for Stakeholders
Investors should target developers of modular pre-analytical automation systems and data management integration software. Capitalizing on interoperability solutions offers the highest return as laboratories increasingly demand multi-vendor platform consolidation.
Conclusion and Key Takeaways for Industry Stakeholders
The transition toward fully automated pre-analytical workflows is irreversible. Market participants must prioritize software interoperability, modular scalability, and robust aftermarket support to secure long-term contracts with major hospital groups and reference laboratories.
Research Methodology: How baseline estimates and market figures are triangulated
Our analytical framework triangulates trade registry data, primary stakeholder interviews with laboratory directors, and secondary macroeconomic indicators. Bottom-up revenue aggregation of key market players is cross-verified against regional healthcare expenditure reports to ensure absolute data fidelity.
Scope of the Report: Coverage parameters, parameters, and analytical limitations
This report covers global revenue performance across specified product types, workflows, automation levels, and applications from 2026 through 2033. Excluded from this scope are manual sample collection consumables and post-analytical diagnostic interpretation software not directly tied to core pre-analytical tracks.
Recent Developments: Corporate announcements, strategic partnerships, and product launches
Recent market activity highlights aggressive R&D investments by firms like Tecan Group Ltd. and Hamilton Company in modular liquid handling and automated sample storage. Strategic mergers focus on enhancing AI-driven barcode sorting and laboratory information integration capabilities.